Bitcoin options priced larger short-term swings ahead of this week’s central-bank decisions, with derivatives analytics provider Laevitas’s Oct. 26 snapshot showing a premium over recently realized price swings. Buyers holding through the announcements face the risk that some of that premium fades before Bitcoin moves enough to offset it.
The Federal Reserve’s October calendar schedules today’s decision for 2 p.m. Eastern, followed by a 2:30 p.m. press conference.
Implied volatility reflects the movement priced into options. Laevitas reported its seven-day at-the-money reading at 36.5%, up from 32% a week earlier. At-the-money options have strike prices near the underlying market level. The seven-day reading was close to its 30-day equivalent of 37%, bringing short-term implied volatility close to longer maturities.
In its separate seven-day implied-versus-realized comparison, Laevitas paired 36.1% implied volatility with 26.9% realized volatility, a reported 9.2-volatility-point gap.
Realized volatility measures movement that has already occurred. All these readings are annualized. The gap therefore compares future uncertainty with past price action.
That is a change in setup from CryptoSlate’s Oct. 12 coverage, which described cheaper short-term volatility before CPI.
Downside skew remained near its median
The relative price of downside protection remained near its usual level. Laevitas put Bitcoin’s 30-day 25-delta skew at minus 4.64 volatility points, almost matching its minus 4.62 median and ranking at the 49th percentile over 52 weeks.
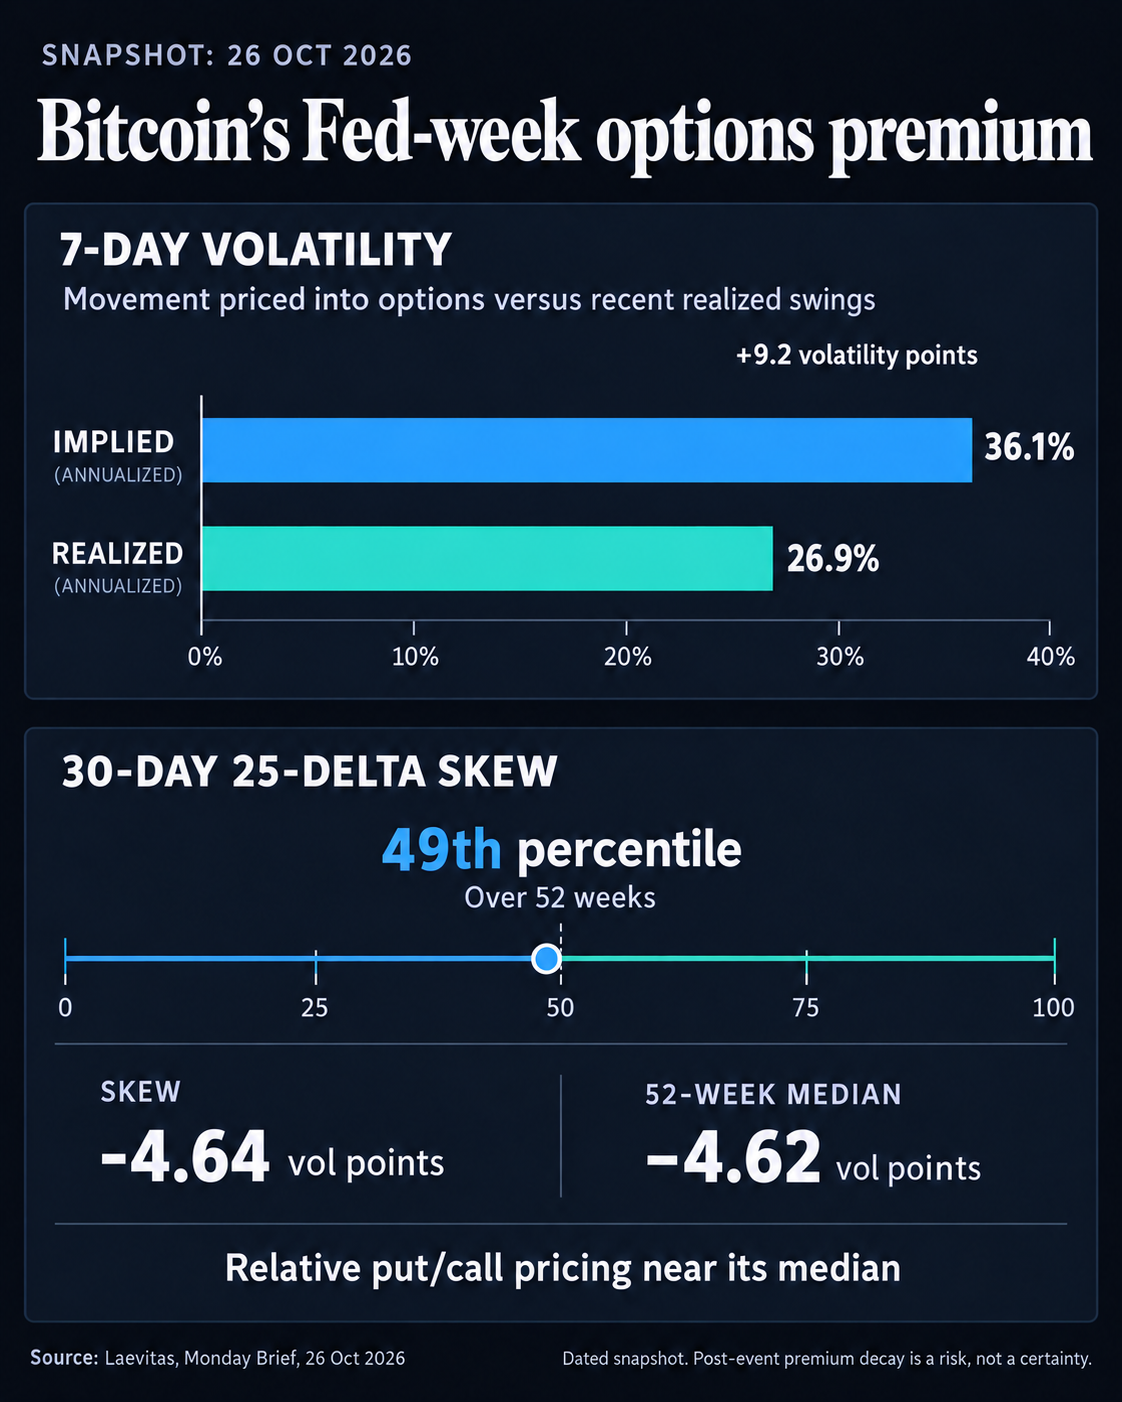
Skew compares implied volatility for puts and calls at corresponding deltas. Under Laevitas’s convention, the negative reading indicated a put premium. That places this 30-day put-versus-call measure near its usual level even as short-term implied volatility rose.
Laevitas described the short-dated pricing as reflecting a packed calendar spanning the Fed, European Central Bank and Bank of Japan decisions, economic releases, earnings and Friday’s Deribit monthly expiry. The 9.2-point spread cannot be assigned entirely to the Fed.
Options retain sensitivity to volatility and time. Holding other inputs constant, lower implied volatility reduces a purchased option’s value, while time passing erodes its remaining time value. A favorable Bitcoin price move can offset those effects.
If the decisions pass without enough market movement and implied volatility retreats, buyers can lose part of what they paid for event exposure. Surprises or further uncertainty can sustain the premium instead.